Order-to-cash (O2C) is the end-to-end business process that starts when a customer places an order and ends when the customer’s payment is received, applied to the right invoice and recorded in the general ledger. It covers order management, credit management, fulfillment, invoicing, accounts receivable, collections, dispute resolution and cash application.
| Item | Answer |
|---|---|
| Also called | O2C, OTC, order-to-cash cycle |
| Starts with | A customer order |
| Ends with | Payment applied and reconciled in the general ledger |
| Owned by | Sales operations, credit, billing, accounts receivable and treasury, usually led by finance |
| Main goal | Turn orders into cash quickly and accurately, with a good customer experience |
| Key metric | Days sales outstanding (DSO) |
Why the Order-to-Cash Process Matters
O2C determines how quickly revenue becomes usable cash. Every delay, from a credit check that holds an order to an invoice with the wrong price, adds days before the company is paid. An efficient O2C process:
- Improves cash flow and working capital by shortening the time between sale and payment.
- Lowers DSO, the average number of days it takes to collect after a sale.
- Reduces revenue leakage from billing errors, unresolved deductions and write-offs.
- Improves the customer experience through accurate invoices, clear communication and easy payment.
- Gives finance leaders visibility into receivables, risk and expected cash.
The impact is easy to quantify. A company with $500 million in annual revenue collects about $1.37 million per day ($500M ÷ 365), so reducing DSO by a single day releases roughly $1.4 million of working capital.
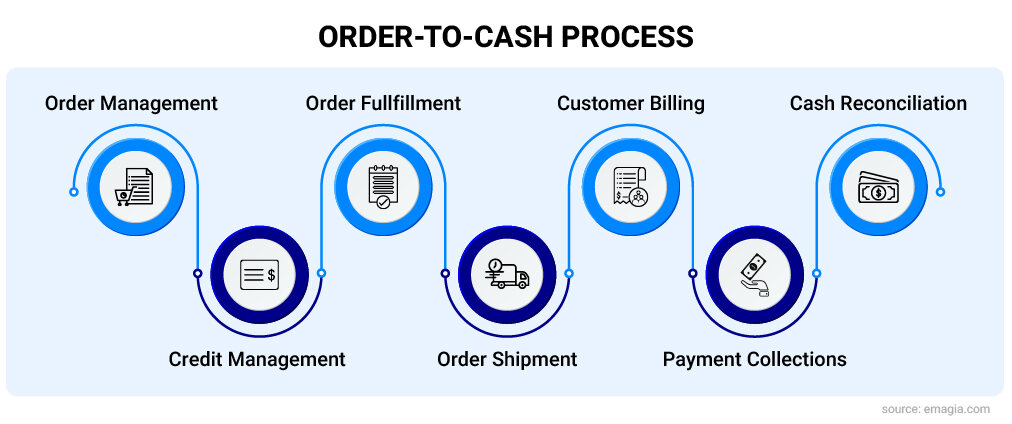
The 8 Steps of the Order-to-Cash Process
| Step | What happens | Common bottleneck |
|---|---|---|
| 1. Order management | The order is received, validated and entered | Manual entry errors, incomplete orders |
| 2. Credit management | Customer creditworthiness and limit are checked | Orders held for slow credit reviews |
| 3. Fulfillment and shipping | Goods are shipped or services delivered | Delivery issues that later trigger disputes |
| 4. Invoicing | An accurate invoice is created and sent | Late or incorrect invoices |
| 5. Accounts receivable management | Open invoices are tracked and aged | No real-time view of at-risk invoices |
| 6. Collections | Customers are reminded and followed up | Reactive, one-size-fits-all follow-up |
| 7. Dispute and deduction management | Short payments and claims are resolved | Disputes tracked in email and spreadsheets |
| 8. Cash application and reconciliation | Payments are matched to invoices and posted | Remittances arriving separately from payments |
Reporting and analytics run across all eight steps. Each step also affects the others: slow cash application leaves collectors chasing invoices that are already paid, and collection history feeds back into credit decisions.
1. Order Management
The process begins when a customer places an order through sales, a portal, EDI or email. The order is checked for pricing, quantities, terms and customer details, then entered into the ERP. Errors here carry through to the invoice, so accurate order capture is the cheapest way to prevent later disputes.
2. Credit Management
Before the order is released, the credit team checks whether the customer can pay. For new customers this means analyzing financial statements, credit agency reports and trade references; for existing customers it also includes internal payment history. The result is a credit limit and payment terms.
Slow manual reviews put orders on hold and delay revenue. Automated credit risk management scores customers in real time, adjusts limits as risk changes and releases low-risk orders immediately.
3. Fulfillment and Shipping
The goods are picked, packed and shipped, or the service is delivered. Proof of delivery matters for finance: shortages, damage and late deliveries are among the most common reasons customers later short-pay an invoice.
4. Invoicing
Once the order is fulfilled, an invoice is created and delivered through the channel the customer requires, such as email, EDI, a customer portal or post. Invoices must be both timely and accurate. A company that invoices a week after shipping adds a week to its collection time, and invoices with wrong prices, quantities or purchase order numbers are a leading cause of payment delays. Electronic invoicing standardizes formats and helps meet country-specific e-invoicing rules.
5. Accounts Receivable Management
After invoicing, the amount sits in accounts receivable until it is paid. The AR team tracks open invoices, monitors aging and segments customers by risk and payment behavior so that collections effort goes where it matters. An AR aging report is the core tool for this step.
6. Collections
Collectors follow up on open and overdue invoices by email, phone and portal. They need accurate, current information; otherwise they waste time chasing invoices that have already been paid or are blocked by a dispute. Collections automation sends reminders before and after due dates and prioritizes accounts by predicted payment risk, while self-service portals let customers check balances and pay without contacting AR.
7. Dispute and Deduction Management
Customers sometimes pay less than the invoiced amount because of pricing errors, damaged goods, promotions or missing proof of delivery. Each short payment must be investigated, routed to the right team and resolved, or it becomes revenue leakage. Dispute data is also valuable upstream: recurring reasons point to fixable problems in ordering, shipping or billing. Learn how to resolve customer payment disputes faster.
8. Cash Application and Reconciliation
Cash application matches each incoming payment to the invoices it pays and posts it to the general ledger. With checks, remittance details arrive with the payment. With electronic payments, remittance information often arrives separately by email, PDF or portal, adding a matching step. Although cash application comes last, it feeds critical information back to collections, credit and sales. AI-based matching can apply payments even when remittance details are incomplete and routes only the exceptions to people.
Order-to-Cash Process Example
A manufacturer receives an order for $50,000 of parts on Net 30 terms. Here is how the cycle might run:
| Day | Event |
|---|---|
| 0 | Customer places the order; it is validated and entered |
| 1 | Credit check passes and the order is released |
| 3 | Goods ship and delivery is confirmed |
| 4 | Invoice is sent; payment is due on day 34 |
| 30 | Automated reminder is sent before the due date |
| 41 | Customer pays $48,500, deducting $1,500 for a damaged item |
| 43 | Payment is applied; the $1,500 deduction is routed for review |
| 50 | Deduction is validated with proof of delivery and resolved |
The order-to-cash cycle took 43 days to collect most of the cash and 50 days to close fully. The biggest controllable delays were the 7 days the customer paid late and the 7 days needed to resolve the deduction.
Order-to-Cash vs. Quote-to-Cash vs. Procure-to-Pay
| Order-to-cash (O2C) | Quote-to-cash (Q2C) | Procure-to-pay (P2P) | |
|---|---|---|---|
| Perspective | Seller | Seller | Buyer |
| Starts with | Customer order | Price quote or proposal | Purchase requisition |
| Ends with | Customer payment applied | Customer payment applied | Supplier payment made |
| Main teams | Credit, billing, AR, collections | Sales, pricing, contracts, plus O2C teams | Procurement, accounts payable |
| Key metric | DSO | Quote-to-close time, DSO | DPO |
Quote-to-cash includes O2C plus the earlier sales steps of configuring, pricing and quoting. Procure-to-pay is the mirror image of O2C: one company’s O2C is its customer’s P2P.
Order-to-Cash KPIs
| KPI | What it measures |
|---|---|
| Days sales outstanding (DSO) | Average days to collect after a sale |
| Collection effectiveness index (CEI) | Share of collectible receivables actually collected |
| Average days delinquent (ADD) | How late customers pay beyond terms |
| Invoice accuracy rate | Share of invoices issued without errors |
| Auto-match rate | Share of payments applied without manual work |
| Dispute resolution time | Average days to resolve a dispute or deduction |
| Order hold time | Time orders wait for credit approval |
| Bad debt as % of revenue | Receivables written off as uncollectible |
Common Order-to-Cash Challenges
- Disconnected systems: multiple ERPs and spreadsheets across business units fragment the view of customers and receivables.
- Manual cash application: remittances in emails and PDFs must be matched by hand.
- Reactive collections: follow-up starts only after invoices are overdue.
- Slow dispute resolution: deductions sit unresolved and become write-offs.
- Order holds: slow credit reviews delay shipments and revenue.
- Poor master data: inaccurate customer records and payment references undermine every step.
- Global complexity: multiple currencies, languages and e-invoicing rules.
O2C Maturity: Manual vs. ERP-Based vs. AI-Driven
| Area | Manual | ERP-based | AI-driven |
|---|---|---|---|
| Credit approvals | Manual review | Rule-based limits | Predictive risk scoring |
| Collections | Reactive calls and emails | Scheduled reminders | Prioritized by predicted payment risk |
| Cash application | Manual matching | Basic matching rules | AI matching of unstructured remittances |
| Disputes | Email and spreadsheets | Basic case tracking | Automatic classification and routing |
| Visibility | Periodic spreadsheet reports | Standard dashboards | Real-time and predictive analytics |
| Typical outcome | High DSO, frequent errors | Moderate efficiency | Lower DSO, fewer exceptions |
Signs it is time to automate: DSO is rising, a large share of payments still needs manual matching, collections are reactive, deductions are piling up, or multiple ERPs make receivables hard to see in one place.
How AI Improves the Order-to-Cash Process
AI handles high-volume, repetitive work and flags the exceptions that need human judgment:
- Credit: scores risk from financial, payment and external data to release good orders faster.
- Collections: predicts which invoices will be paid late and recommends who to contact, when and how.
- Cash application: reads remittance data from emails and PDFs and matches payments automatically.
- Disputes: classifies deductions by reason and routes them to the right team.
- Forecasting: predicts invoice-level payment dates to improve cash flow forecasting.
For the full business case, see the benefits of accounts receivable automation.
See how ConvaTec transformed order-to-cash across its global business services. Watch the story
Best Practices to Optimize the Order-to-Cash Cycle
- Get the order right first time: validate pricing, terms and customer data at entry.
- Automate credit decisions: release low-risk orders instantly and focus reviews on exceptions.
- Invoice the same day: send accurate invoices as soon as goods ship or services are delivered.
- Remind before the due date: proactive reminders prevent lateness instead of chasing it.
- Make paying easy: offer digital payment options and a self-service portal.
- Resolve disputes fast and fix root causes: use deduction reason codes to correct upstream problems.
- Automate cash application: apply payments quickly so collections and credit work from current data.
- Measure and review monthly: track DSO, CEI, auto-match rate and dispute cycle time against targets.
How to Implement O2C Automation
- Assess: map the current process and set baseline KPIs such as DSO, CEI and auto-match rate.
- Clean data: standardize customer master data, payment references and ERP structures.
- Pilot: start with one process (often cash application or collections) in one business unit or region.
- Roll out: expand across entities and regions with consistent workflows.
- Optimize: use performance data and AI recommendations to keep improving.
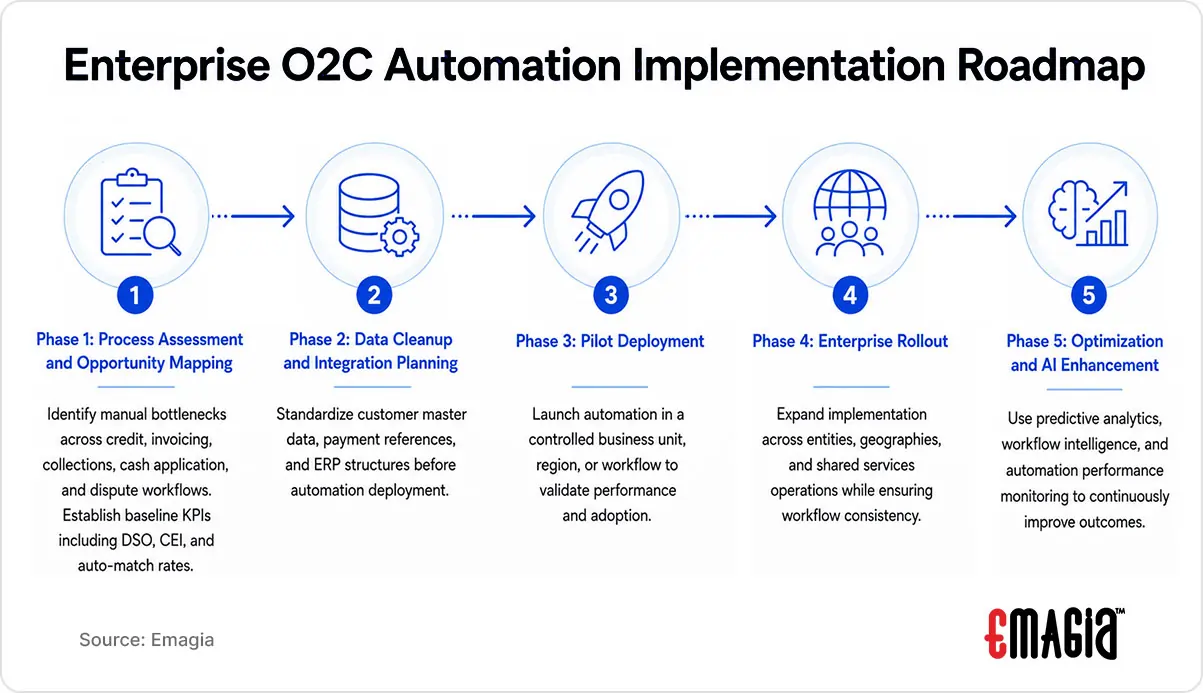
Technology alone does not guarantee results. Successful programs redefine collector roles around exceptions, align shared services processes, assign clear ownership in finance leadership and set KPI accountability.
How to Evaluate an Order-to-Cash Automation Platform
- ERP integration: prebuilt connectors for your ERPs (for example SAP, Oracle, NetSuite, Microsoft Dynamics) and banks.
- Coverage: credit, invoicing, collections, disputes, deductions and cash application in one platform.
- AI depth: predictive capabilities rather than only rule-based workflows.
- Global scale: multi-entity, multi-currency and multi-language support.
- Analytics: executive dashboards for DSO, CEI, aging and forecasts.
- Controls: audit trails, approvals and role-based access.
- Implementation support: realistic timelines and references from similar companies.
How Emagia Supports Order-to-Cash
Emagia’s AI-powered order-to-cash platform brings credit, collections, cash application, deductions and analytics into one system that integrates with existing ERPs. Finance teams use it to release orders faster, prioritize collections, apply cash automatically, resolve deductions sooner and see receivables across regions and currencies in one place.
Shorten the O2C cycle with digital invoicing and payments. Read the eBook
Order-to-Cash Process FAQs
What is the order-to-cash process?
Order-to-cash (O2C) is the end-to-end process from receiving a customer order to collecting payment and recording it in the general ledger. It includes order management, credit management, fulfillment, invoicing, accounts receivable, collections, dispute resolution and cash application.
What are the steps in the order-to-cash process?
The eight steps are order management, credit management, fulfillment and shipping, invoicing, accounts receivable management, collections, dispute and deduction management, and cash application and reconciliation. Reporting runs across all of them.
What is the difference between order-to-cash and procure-to-pay?
Order-to-cash is the seller’s process for turning customer orders into cash. Procure-to-pay is the buyer’s process for purchasing goods and paying suppliers. One company’s order-to-cash is its customer’s procure-to-pay.
What is the difference between order-to-cash and quote-to-cash?
Quote-to-cash covers the whole sales cycle, starting with a price quote and including contract and order creation. Order-to-cash starts once the order is placed, so it is the later part of quote-to-cash.
Who is responsible for the order-to-cash process?
O2C involves sales operations, credit, billing, accounts receivable, collections and treasury. It is usually owned by finance, often under the CFO, controller or a shared services leader.
What KPIs measure order-to-cash performance?
Common O2C KPIs are days sales outstanding (DSO), collection effectiveness index (CEI), average days delinquent, invoice accuracy rate, auto-match rate, dispute resolution time, order hold time and bad debt as a percentage of revenue.
How does automation improve the order-to-cash process?
Automation speeds up credit decisions, sends invoices and reminders on time, prioritizes collections by risk, matches payments to invoices automatically and routes disputes to the right team. This lowers DSO, reduces manual work and gives real-time visibility into receivables.
What are the biggest order-to-cash challenges?
The most common challenges are disconnected ERP systems, manual cash application, reactive collections, slow dispute resolution, order holds from slow credit reviews, poor master data and the complexity of operating across countries and currencies.
How long does it take to implement O2C automation?
It depends on scope, ERP complexity, number of entities and data quality. Most enterprises roll out in phases, starting with one process such as cash application or collections in one business unit, then expanding.